Quick Answer
Usually not all of it stays yours. A home you bought before marriage starts out as your separate property, but principal paid down with marital income takes a proportional share of the appreciation with it, and that share becomes community property. Having only your name on title doesn't change the result.
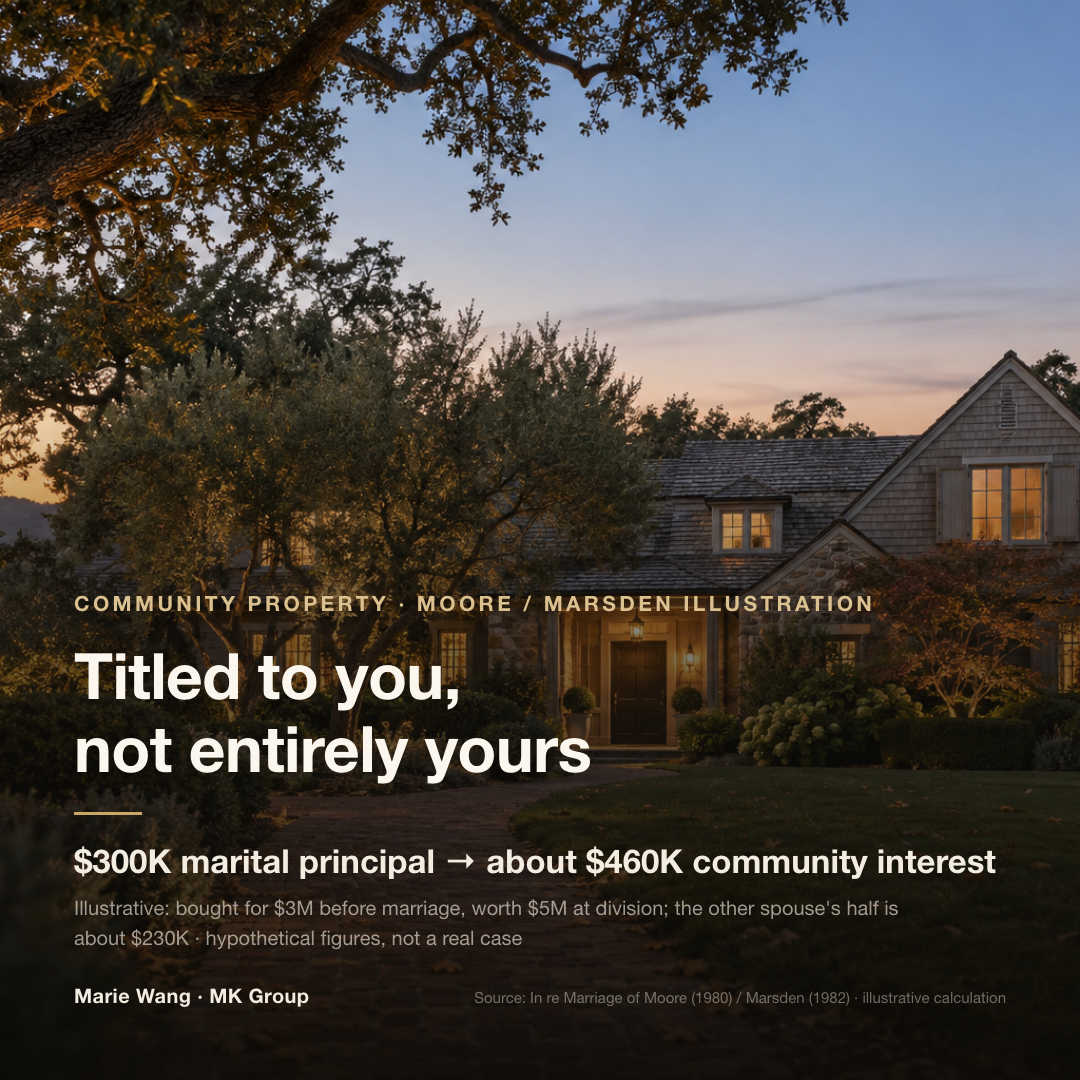
California is a community property state. How a home is divided turns on when it was bought, whose money made the down payment and whose money paid the mortgage, rather than on whose name is on title. Marie Wang (DRE# 02110980), co-founder of MK Group, put it plainly in an October 2026 video on her YouTube channel (@MarieWang, 44K+ subscribers): selling the house is a transaction question; dividing the money is a legal one. In this article's illustrative calculation, a home bought for $3M before marriage and worth $3.4M at the wedding, with $300,000 of principal paid from salaries during the marriage and worth $5M at division, holds a community interest of about $460,000 — about $230,000 of it attributable to the other spouse.
Who this article is for
- Owners who, before marrying, bought a $3M-plus single-family home in Palo Alto, Los Altos, Menlo Park, Cupertino, Saratoga or Atherton, have paid the mortgage together since, and now face separation or divorce
- Tech households whose net worth sits largely in RSUs and options, and who need to negotiate the house and the stock together
- The spouse who wants to keep the home — buying out the other's interest and carrying the mortgage alone
- Owners holding a 2.x%–3.x% mortgage who don't want the divorce to cost them that loan
- Couples who have decided to sell but haven't fully agreed on price and timing
Three core dimensions
A premarital home raises three questions in a divorce: what kinds of interest sit inside the house, who the loan follows, and who the tax basis follows. Three different professionals answer them — the attorney, the lender and the CPA.
Dimension one: money and timing decide what interests sit in the house
Many owners assume that whoever's name is on title owns the house. In California, that assumption doesn't hold. Ownership is reflected in the recorded deed and in title records, and the name there is only the starting point. California presumes that property acquired during marriage is community property (Family Code §760). Property owned before marriage, or acquired by gift or inheritance, is separate property (Family Code §770). A home bought during the marriage is generally still presumed community property, even when title is in one spouse's name alone.
What makes a premarital home difficult is that a single house can hold both kinds of interest at once. Under the method set out in two California cases, In re Marriage of Moore (1980) and In re Marriage of Marsden (1982), principal paid down with marital income gives the community a share of the appreciation during the marriage, in proportion to principal paid divided by purchase price. Only principal counts; interest, property taxes and insurance do not. If the home was refinanced with cash out during the marriage, the calculation becomes considerably more complicated.
The rule runs the other way, too. If a home bought during the marriage in both names was purchased with a down payment from one spouse's premarital savings, that contribution can generally be reimbursed first under Family Code §2640 — without interest and without appreciation — unless that spouse waived the right in writing.
Beyond the house, equity is where Silicon Valley households most often miscount. Unvested RSUs and options are not necessarily all yours, even if they vest after you separate. It depends on the grant date, whether the award rewards past work or requires future service, and the date of separation — under Family Code §70, the point at which one spouse has expressed the intent to end the marriage and their conduct is consistent with it. Courts often allocate these awards with a time-based formula (see In re Marriage of Hug and In re Marriage of Nelson). These are determinations for a family law attorney; where the accounts are complex, a forensic accountant may be needed to trace them.
Dimension two: title and the loan are two separate matters
Start with whose names are on the loan. If you took out the mortgage alone before the marriage and never refinanced it together, it stays yours when you keep the house, and there is no one to release. What follows applies to joint loans — a refinance you both signed during the marriage, or a home you bought together. Suppose the house ends up with you and the deed is changed to your name alone. If your spouse is a co-borrower, they are still on the loan. The mortgage is a debt both of you owe the lender, and a change of title doesn't touch it. The federal Garn–St Germain Act (12 U.S.C. §1701j-3(d)(7)) generally bars a lender from calling the full loan due solely because the home was transferred to a spouse under a divorce decree or property settlement agreement. But it only keeps the loan from being accelerated. It does not release the departing spouse from repayment.
A release takes the servicer's approval. Either the spouse keeping the home takes over the loan through an assumption with a release of liability — preserving the original rate and terms while removing the other spouse — or that spouse refinances in their own name. Whether either is possible depends on the loan type, the servicer's policy and the remaining spouse's qualifications on their own; for the jumbo loans common in the Bay Area, the answer varies by institution. If the original loan carries a 2.x%–3.x% rate, ask the servicer first and discuss a refinance second.
Dimension three: the tax basis travels with the house, and a buyout doesn't add to it
If you pay $2M to buy out your spouse's interest, that $2M generally does not become your new cost basis. Under IRC §1041, no gain is recognized on a transfer between spouses, or on a transfer to a former spouse incident to divorce — within one year after the marriage ends, or related to the end of the marriage and generally completed within six years under the divorce instrument. The spouse who receives the property takes over the original basis, known as carryover basis. Tax not paid today hasn't disappeared; it can come back when the home is eventually sold. If the receiving spouse is a nonresident alien, this rule does not apply (IRC §1041(d)).
Two more rules belong in the same conversation. The home-sale exclusion under IRC §121 is up to $500,000 on a joint return and generally up to $250,000 per person filing separately. For the spouse who moves out, time the other spouse lives in the home under the divorce or separation instrument can generally still count as use as a principal residence (§121(d)(3)(B)). For more, see Selling a Long-Held Bay Area Home, the $500K Gain Exclusion Barely Dents It—How Much Tax Is Owed on the Rest? On property tax, a transfer to a spouse or former spouse under a divorce decree or property settlement agreement does not trigger a Prop 13 reassessment (Revenue and Taxation Code §63); claim the exclusion on the change-in-ownership statement filed at transfer. For background, see You Bought a $10M+ Bay Area Home—Why Does a Second Property-Tax Bill Arrive Months After Closing?
The numbers: two illustrative calculations
Both tables below are simplified illustrations using hypothetical figures, not real cases. Actual amounts depend on the calculations of your attorney, the court and the lender.
Illustration 1: how much community property sits inside a premarital home
Key numbers first: a home bought for $3M before marriage, titled in one spouse's name alone, has $300,000 of principal paid down with marital income and is worth $5M at division. Under the Moore/Marsden method, the community percentage is 10%, the community interest is about $460,000, and the titled spouse may owe the other about $230,000.
| Item | Amount | Character |
|---|---|---|
| Purchase price before marriage (down payment $900,000 + loan $2,100,000) | $3,000,000 | — |
| Down payment (premarital savings) | $900,000 | Separate |
| Principal paid before marriage | $60,000 | Separate |
| Appreciation before marriage ($3M at purchase → $3.4M at marriage) | $400,000 | Separate |
| Principal paid during marriage with marital income | $300,000 | Community |
| Appreciation during marriage ($3.4M at marriage → $5M at division) | $1,600,000 | Apportioned |
| Community percentage = $300,000 ÷ $3,000,000 | 10% | — |
| Community interest = $300,000 + 10% × $1,600,000 | $460,000 | Community; about $230,000 each |
| Separate interest = $900,000 + $60,000 + $400,000 + 90% × $1,600,000 | $2,800,000 | Separate |
| Check: value $5M − remaining loan $1.74M = equity | $3,260,000 | = $2.8M + $460,000 |
What to remember: of the $460,000, only $300,000 is principal actually paid in. The other $160,000 is marital appreciation that the $300,000 carries with it at a 10% share, so the more the home gains during the marriage, the larger that piece becomes. A house that is "100% mine" on title can still hold a community interest of about $460,000.
Illustration 2: what keeping the original loan is worth each month
Key numbers first: on the same $1.74M balance, amortized over 30 years with principal and interest, the monthly payment is about $7,336 at 3% and about $10,998 at 6.5% — roughly $3,660 more each month, or about $44,000 a year.
| Rate (30-year principal and interest, $1,740,000 balance in each case) | Approx. monthly payment | More per month than at 3% |
|---|---|---|
| 3.0% | $7,336 | — |
| 6.0% | $10,432 | About $3,096 |
| 6.5% | $10,998 | About $3,662 |
| 7.0% | $11,576 | About $4,240 |
What to remember: this table compares rates alone. If you keep the original loan, the actual payment follows the original contract and its remaining term; for current rates, check a public weekly survey such as Freddie Mac's PMMS. If the buyout money also has to come from a cash-out refinance, the new loan is larger and the gap only widens. An assumption can preserve the rate, but it doesn't produce buyout cash. That money has to come from other assets — which leads back to the question of tax basis.
Data source: Public text of the California Family Code, the Internal Revenue Code and 12 U.S.C. §1701j-3, and California case law; both tables are arithmetic illustrations using hypothetical figures
Updated: 2026-10
Scope: California homeowners facing divorce, Bay Area single-family homes of $3M and up; not a determination of the interests in any individual case, and not a loan quote
Three paths: sell, buy out, or hold together for now
A divorce doesn't have to mean a sale. In practice there are three common paths, and Marie singles out the third. "Not selling yet" can't be settled in a sentence. Who lives in the home for the next two years, who pays the mortgage, property tax, insurance and repairs, and how a $300,000 gain — or a decline — two years on will be shared all need to be put in writing the moment you decide to keep holding it together.
| Path | What to agree in writing | How the loan is handled | Tax points | Main risk |
|---|---|---|---|---|
| Both agree to sell | List price, floor price, who may accept or counter, how the proceeds are split | Paid off from the proceeds at closing | The home-sale exclusion follows your filing status at the time of sale: up to $500,000 on a joint return, generally up to $250,000 per person filing separately | A disagreement over price stalls the offer, and the buyer walks |
| One spouse buys out the other | Valuation method, buyout price, source and timing of payment | Assumption with release of liability, or a new loan in the remaining spouse's name alone | Generally not taxed at the time; the remaining spouse takes over the original basis; property tax is generally not reassessed | The buyout payment doesn't add to basis, and the tax returns at a future sale |
| Hold together for now | Who lives there; who pays the mortgage, property tax, insurance and repairs; when and how the home will be sold or bought out; how gains and losses are shared | Both spouses remain jointly liable on the loan | Whether the spouse who moved out can keep counting residence time depends on whether the divorce documents say so | If it isn't in writing, you will negotiate again in two years, whether prices rise or fall |
Whichever path you take, one procedural limit applies. Once a divorce petition is filed and served, the standard restraining orders on the summons (Family Code §2040) generally bar either spouse from selling, transferring or borrowing against property without the other's written consent or a court order. Even when title is in one spouse's name, California title companies often require the other spouse to sign an interspousal transfer deed or a consent before a sale. "List now, work it out along the way" doesn't work in practice, and procedurally it may not be permitted.
What MK Group sees on the ground
The points below come from Marie Wang's video and reflect what she has seen, and what she warns sellers about, as a listing agent in divorce sales. They are not a review of any single transaction.
When the two of you disagree, the offer is the first thing lost
Marie describes a scene she considers typical. A divorcing couple already had an offer in hand. One spouse was exhausted and wanted to accept it and be done with the whole thing; the other thought the price was too low and insisted on negotiating further. The buyer was waiting, escrow was waiting, the buyer's lender was waiting — and so was she, as the listing agent. The disagreement between the two became a cost of the transaction itself. As the delay dragged on, the buyer walked away and bought another home in the same neighborhood. A good offer was gone, and so was the market window.
Selling is a transaction question; dividing the money is a legal one
Marie is emphatic on this point. The title company and escrow will not split the proceeds down the middle just because two names are on title. They act on the agreement both spouses have signed, any court order and the transaction documents, which is why the agreement itself matters most. She is equally clear about where an agent's role ends: the agent handles how the home is sold, what it is worth and how to bring it to a clean close. The marriage, and how the property is characterized, belong with the attorneys.
Ask about the loan before deciding who keeps the house; bring in the CPA before the final agreement
Marie also warns about a common regret: a couple agrees on who keeps the house, then discovers that no one ever asked about the loan. Whether one person can carry it alone, whether the lender will approve that, and whether the original 2.x%–3.x% loan can be assumed should all be settled before the decision is made. The same goes for tax. In a split of "you take the house, I take the other assets," both sides may show $5M on paper, but a house, stock and cash can be worth very different amounts after tax. The CPA and the attorney need to be involved before the final agreement is signed.
Marie closes the video on a personal note. No two people share a life without arguing, she says, and if there is still room to talk, she would far rather couples never reach the point of selling a home over a divorce.
Common Misconceptions
Misconception 1: "Only my name is on title, so the house is entirely mine"
Your name is only the starting point. If principal on a home bought before marriage was paid down with salary during the marriage, the community takes a share of that principal and of the appreciation under the Moore/Marsden method. In this article's illustration, $300,000 of principal paid during the marriage corresponds to a community interest of about $460,000.
Misconception 2: "Both our names are on title, so we each get half"
That doesn't hold either. If a home bought during the marriage in both names was purchased with a down payment from one spouse's premarital savings, that amount can generally be reimbursed first to the contributing spouse under Family Code §2640 (without interest or appreciation), and only the remaining community portion is divided equally — unless the contributing spouse waived reimbursement in writing.
Misconception 3: "Once the deed is in my name alone, the loan has nothing to do with my spouse"
If your spouse is a co-borrower, taking their name off the deed leaves them a borrower on the loan. If the spouse who keeps the house later stops paying, the spouse who left will see the damage on their own credit. Ending that liability requires the servicer to approve a release of liability, or the remaining spouse to take out a new loan alone.
Misconception 4: "If I pay $2M to buy out my spouse, that $2M becomes my new cost basis"
Usually not. Under IRC §1041, a transfer between spouses incident to divorce triggers no recognized gain at the time; the receiving spouse takes over the original basis, and the buyout payment is not added to it. When the home is eventually sold, the deferred tax can come back — and once you file as a single taxpayer after the divorce, the home-sale exclusion is generally only $250,000.
Misconception 5: "We'll list first and work things out as we go"
Listing without agreement on price most often ends with the offer slipping away while you wait. And once a divorce petition is served, the standard restraining orders under Family Code §2040 generally bar either spouse from disposing of property without the other's written consent or a court order. Before you list, write into an agreement you both sign: the floor price, who may accept or counter, and how the proceeds will be split.
Misconception 6: "My RSUs vest after we separate, so they're all mine"
Not necessarily. Beyond the vesting date, courts look at the grant date, whether the award rewards past or future work, and the actual date of separation, then allocate with a time-based formula. Before negotiating the house and the stock together, have your attorney confirm which equity awards count as community property, and in what proportion.
Next steps
- Pull together three sets of records first. The purchase date and the paper trail for the down payment; payment records from before and during the marriage, with principal separated from interest; and whether the home was ever refinanced with cash out. Hand them to a family law attorney to sort separate interests from community interests.
- Call your loan servicer. Ask whether one spouse can carry the loan alone, whether the servicer accepts an assumption or an assumption with a release of liability, and what qualification documents it requires. Until you have the answer, don't decide who keeps the house.
- Have a CPA compare the options after tax. Run "sell and split the proceeds" and "one spouse buys out the other" separately: the original basis, the home-sale exclusion ($500,000 joint, $250,000 filing separately) and the capital gain on a future sale, with RSUs and options included.
- If you'll hold the home together for now, sign a written agreement. Spell out who lives there; who pays the mortgage, property tax, insurance and repairs; when, and on what valuation, the home will be sold or bought out; and how a gain is split or a loss shared.
- If you decide to sell, agree on price before you list. Write into an agreement you both sign: the floor price, who may sign a counteroffer, and how the proceeds will be divided. Then have your agent set the price and the timing of the launch.
The statutes and cases cited here may be amended, and different facts lead to different conclusions. This article is for decision-making education and does not constitute legal or tax advice; confirm specifics with your attorney and CPA, and confirm loan matters with your lender and servicer.