Direct answer
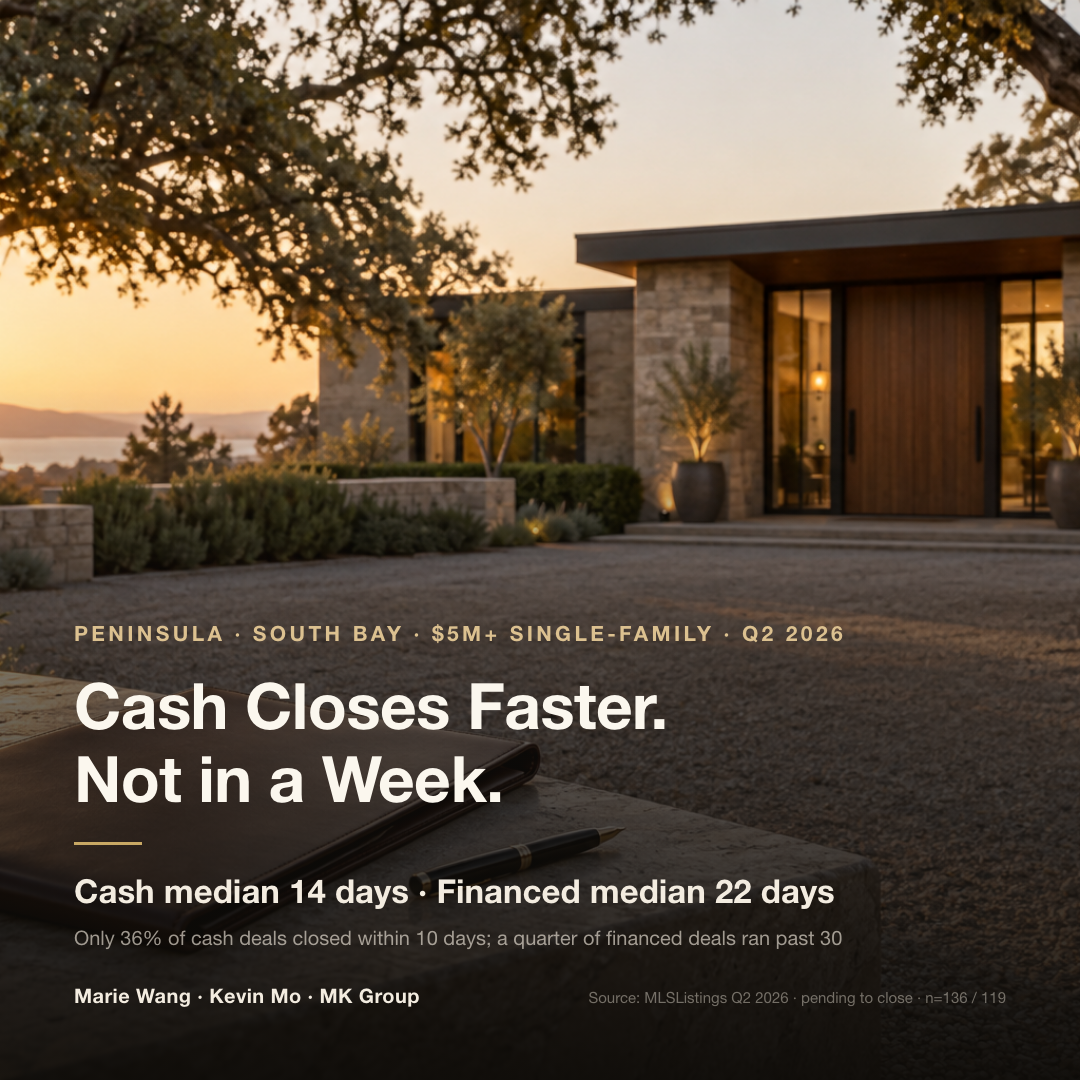
Slower than most buyers expect. In Q2 2026, $5M+ single-family homes in nine Peninsula and South Bay cities closed a median 14 days after going pending when paid all-cash, and only about a third (36%) closed within 10 days. Financed purchases took a median 22 days, and roughly a quarter ran past 30 (MLSListings, n=136 / 119).
Who this article is for
- Families planning an all-cash purchase above $5 million in Palo Alto, Atherton, Los Altos Hills, Hillsborough, or a neighboring town who want to know how many weeks realistically sit between a signed contract and the keys
- Buyers taking title through an LLC, a family trust, or an operating company, who need authority documents and a funding route in place early
- Buyers whose funds are held overseas and will arrive by international wire
- Families working to a fixed landing date — a school start, a lease ending, an assignment start, an international move — who need the closing date and the move-in date on one calendar
- Buyers using a jumbo or private-bank loan above $5 million who want to know how many extra days financing actually adds
Three things that actually decide the timeline
The length of escrow is a number both sides agree to in the contract. The buyer cannot shorten it alone. Where it lands depends on three things.
One: who is paying — an individual, a trust, or an entity
An all-cash purchase in an individual's name is the simple case: funds arrive, documents are signed, the deed records. Once the buyer is an LLC, a family trust, or a corporation, the title company and escrow have to confirm who has authority to sign for that buyer. A trust needs a certificate of trust and the trustee's signature. An LLC needs its operating agreement and member or manager authorization. A corporation needs a board resolution. A newly formed entity also needs an EIN and a bank account in the entity's own name before money can move from the right account. When these papers are started after the contract is signed, they are often the reason 14 days becomes 25.
FinCEN's residential real estate reporting rule (31 CFR 1031.320) briefly put this on center stage: for a residential closing with no mortgage and an entity or trust as buyer, a reporting person in the settlement chain would have to report the beneficial owners. The rule took effect March 1, 2026, was vacated in full by a federal court on March 19, and is now on appeal; FinCEN has said no reports are required while the vacatur stands. Every Q2 closing counted here fell inside that period, so the rule is not what slowed this data. But title companies verify an entity buyer's authority documents regardless, and those papers need to be ready early whichever way the rule goes. The full status is in our piece on FinCEN reporting for all-cash purchases through an LLC or trust.
Two: where the money is coming from — a U.S. account or an international wire
California's good funds rule (California Insurance Code §12413.1) allows escrow to disburse only after funds have actually arrived and become available. Money sitting in the buyer's account and money received into escrow are two different states. From a U.S. account, a wire is usually available the same day or the next. From overseas, the sending bank, any intermediary bank, and the receiving bank may each run compliance review, and a large sum may be sent in tranches — each step can add days. The steadier approach is to move the funds into a U.S. account in the buying entity's name before signing, not to start the wire once the contract is in place.
Three: what the seller needs — move-out timing, rent-back, and title clearance
One overlooked reason the cash median is 14 days rather than 7 sits on the seller's side. The seller may be buying the next home at the same time, waiting for a school term to end, or needing to stay on after closing under a rent-back. Title issues on the seller's side lengthen escrow too: a home held in a trust or an estate needs the trustee's or administrator's authority, the seller's mortgage needs a payoff, and an old lien that surfaces in the preliminary title report has to be cleared. At this price point, the shortest escrow is not always the one the seller wants most.
Real closing timelines across nine cities
The headline numbers first. In Q2 2026, among single-family homes selling for $5 million or more in these nine cities, 136 closed all-cash with a 14-day median; 36% closed within 10 days and only 4% took more than 30. The 119 sales on financed and other terms had a 22-day median; just 11% closed within 10 days, and 25% ran past 30. The higher the price band, the fewer financed sales there are — and the slower they close.
| Price band (single-family, Q2 2026) | All-cash sales | Cash median days | Cash within 10 days | Cash over 30 days | Financed sales | Financed median days | Financed over 30 days |
|---|---|---|---|---|---|---|---|
| $5M–$8M | 75 | 14 | 35% | 1% | 91 | 22 | 23% |
| $8M–$15M | 46 | 13 | 37% | 4% | 22 | 20 | 23% |
| $15M+ | 15 | 15 | 40% | 20% | 6 | 33.5 | 67% |
| Total | 136 | 14 | 36% | 4% | 119 | 22 | 25% |
What to take from this: at $15 million and above, all-cash sales had both the highest share closing within 10 days (40%) and the highest share running past 30 (20%). The band stretches at both ends. When the buyer is an entity or the funds cross a border, deals with their documents and funding route settled in advance can move very quickly; deals without them can fail to close inside a month. This band holds only 15 sales, so the percentages show direction, not precise odds.
Now by city. The headline: the all-cash median barely moves from town to town — 14 days in both Palo Alto and Atherton, 16 in Hillsborough, 13 in Los Altos. Financed medians vary far more: 21 days in Los Altos and Hillsborough, 27.5 in Menlo Park, 31 in Atherton.
| City ($5M+ single-family, Q2 2026) | All-cash sales | Cash median days | Financed and other sales | Financed median days |
|---|---|---|---|---|
| Palo Alto | 24 | 14 | 20 | 21.5 |
| Atherton | 19 | 14 | 7 | 31 |
| Hillsborough | 23 | 16 | 19 | 21 |
| Los Altos | 21 | 13 | 26 | 21 |
| Los Altos Hills | 7 | 10 | 15 | 25 |
| Menlo Park | 14 | 14.5 | 12 | 27.5 |
| Woodside | 14 | 12.5 | 1 | Too few sales |
| Saratoga | 11 | 12 | 16 | 26 |
| Portola Valley | 3 | Too few sales | 3 | Too few sales |
What to take from this: Atherton recorded only 7 financed closings above $5 million in Q2, yet their median reached 31 days, and 4 of the 7 ran past 30. In towns where cash dominates, a financed purchase is already the minority, and it typically carries a large jumbo or private-bank loan whose approval is hard to compress. In Woodside, 14 of the quarter's 15 closings above $5 million were all-cash.
Finally, the cumulative figures most useful for planning. Among all-cash sales, 19% closed within 7 days, 61% within 14, 86% within 21, and 96% within 30. Among financed sales, only 14% closed within 14 days, 49% within 21, 75% within 30, and 92% within 45. Budgeting 3 weeks for cash and 30 to 45 days for a loan covers most real closings. Planning around a one-week cash close would miss in roughly four cases out of five.
How the data is measured: days run from the date the listing moved to Pending in the MLS to the recorded close date (CloseDate). In MLSListings, a contract with contingencies may first be marked Contingent and move to Pending only once they are removed, so for those deals the true count from signing is longer than the table shows. Another 21 records, about 8%, show the same pending and closing date — mostly sales entered into the MLS after they closed. Excluding them, the cash median stays at 14 days, the share closing within 10 days falls to about 30%, and the financed median becomes 23 days. The conclusions hold.
What MK Group sees in the field
One Los Altos Hills purchase in the MK Group case library, from May 2026 (case-019), shows why structure matters more than the day count. The buyer, purchasing through a corporate entity, paid all-cash for a home of roughly $11 million and secured the deal within two weeks. The team led by Marie Wang (DRE# 02110980) and Kevin Mo (DRE# 02127623) did not advise the client to write an ultra-short close for the sake of speed. They first settled three questions — whose name the home is bought in, how the money moves, and how it will be held — and put the title structure, funding route, and authority documents in order before moving escrow forward. Above $10 million, whether the promised closing date holds depends on whether those documents were in place before signing.
A Palo Alto case from April 2026 (case-010) is the reminder from the other direction. An all-cash client with a $10 million budget found a benchmark home and wanted to "sleep on it for one night." By the next morning, another buyer had it under contract. One recommendation from the team's debrief was to have the inspection reports, disclosures, and proof of funds ready before the next showing. Putting proof of funds and entity documents up front is not only about writing an offer quickly — it is also how the closing date promised after signing actually holds.
Working backward from school, the move, and rent-back
The closing date is not the finish line; the move-in date is. Plan in reverse: set the date you must be living in the home, subtract any rent-back period to find the latest workable closing date, then subtract the escrow period to find the latest date to sign. By the data, that means 3 weeks for cash, 30 to 45 days for a loan, plus about a week of moving buffer.
| Situation | Escrow period to budget | Additional time to plan for | Latest signing date |
|---|---|---|---|
| All-cash in an individual's name, funds already in the U.S. | About 3 weeks (covers about 86% of cash closings) | About 1 week after closing for the move, internet, and insurance setup | Move-in date − 1 week − 3 weeks |
| All-cash through a trust, LLC, or corporation | About 3 weeks, with documents complete before signing | Entity formation, EIN, and bank account done during the search | Move-in date − 1 week − 3 weeks, with entity documents earlier still |
| Funds arriving by international wire | About 3 weeks | Wire funds into a U.S. account in the buyer's name before signing | Count from the date funds arrive, not the signing date |
| Jumbo or private-bank loan | 30 to 45 days (covers about 75%–92% of financed closings) | Pre-approval and asset verification done during the search | Move-in date − 1 week − 30 to 45 days |
| Seller needs a rent-back | Per the matching situation above | Add the rent-back period | Move-in date − rent-back days − escrow period |
What to take from this: a rent-back pushes the whole move-in date later, and for that stretch you already own the home — insurance and carrying costs are yours. Under the standard C.A.R. forms, a seller staying briefly after closing typically signs a Seller in Possession addendum, and a stay of 30 days or more usually moves to a Residential Lease After Sale. If the purchase is financed as a primary residence, many lenders set occupancy requirements, so confirm the rent-back length with the lender first.
If the calendar is built around school, the dates that matter are the district's registration deadline and its proof-of-residence requirement, not the first day of class. How to line those up is covered in when the house has to close, and when you have to be living in it, to make fall enrollment. For the order in which to handle insurance, the property tax bill, and the homeowners' exemption after closing, continue with the first 12 weeks after you get the keys.
For arrangements involving a trust, an entity, or cross-border funds, confirm each item with your attorney, CPA, and title company before you sign.
Common mistakes
Mistake one: "All-cash closes in a week"
It can, but it is not typical. Among all-cash $5M+ single-family sales in these nine cities in Q2 2026, only 19% closed within 7 days and 36% within 10; the median was 14 days (MLSListings, n=136). A one-week close needs funds already in a U.S. account, a buyer who is an individual or an entity with complete documents, and a seller willing to hand over the home that fast. Miss any one of the three and the timeline stretches.
Mistake two: "A financed purchase takes at least 30 to 45 days"
At this price point, financed sales move faster than that. On the same basis, sales on financed and other terms closed in a median 22 days; about half (49%) closed within 21 days and about a quarter ran past 30 (MLSListings, n=119). But the higher the price, the slower: only 6 financed sales closed at $15 million and above, with a 33.5-day median. Speed depends mainly on whether pre-approval and asset verification were finished during the search. For how to write financed terms that read close to cash at the offer stage, see how financed buyers compete against all-cash offers.
Mistake three: "The shorter the escrow, the safer the deal"
The escrow period is a commitment written into the contract. Write it short and fail to meet it, and the risk falls on the buyer. For buyers purchasing through an entity or a trust, or with cross-border funds, the steadier path is to settle authority documents, the funding route, and the holding structure first, then choose a closing date that will certainly hold. The Los Altos Hills entity purchase in the case library followed exactly that order: structure first, then escrow.
Mistake four: "The new FinCEN rule means entity cash buyers wait extra weeks"
FinCEN's residential real estate reporting rule took effect March 1, 2026, was vacated by a federal court on March 19, and is on appeal; no reports are required while the vacatur stands. Even while it was in effect, the reporting duty sat with a reporting person in the settlement chain, due by the later of the last day of the month following closing or 30 days after closing — not before closing. What actually affects the day count is the title company's review of an entity buyer's authority documents, and that happens whatever the rule's status.
Next steps
- Write down the date you must be living in the home, then work backward — move-in date minus moving buffer, minus rent-back days, minus the escrow period — to find the latest date to sign. Budget 3 weeks of escrow for cash and 30 to 45 days for a loan.
- If buying through a trust, LLC, or corporation, assemble the certificate of trust or corporate authority documents, the EIN, and a bank account in the entity's name during the search, and ask the title company early which signing documents it will require.
- If the funds are overseas, wire the purchase money into a U.S. account in the buyer's name before signing, and confirm with escrow the receiving account and the standard it uses to treat funds as received.
- If financing, complete pre-approval and asset verification before making an offer, and confirm with the lender how many days appraisal and funding take, and whether it limits the length of a rent-back.
- Treat the escrow period as a negotiable term when you write the offer: ask about the seller's move-out plans and whether a rent-back is needed, then set a closing date both sides can keep.